Navigating the insurance market in Canada can feel overwhelming. Whether you are looking for auto coverage, homeowners insurance, tenant coverage, or commercial insurance, the sheer number of providers and policies available can make decision-making difficult. While buying insurance directly online or through a direct insurer might seem quick, it often leaves policyholders underinsured or paying far more than necessary. This is where a professional insurance broker Canada comes into play. Working with a licensed broker gives you an insider’s advantage: unbiased advice, tailored coverage options, and access to competitive rates from multiple providers.
In this comprehensive guide, we will break down how insurance brokers work Canada, why working with one benefits your wallet and peace of mind, how to locate a top-rated insurance broker near me, and specific regional insights for navigating markets like an insurance broker Ontario or insurance broker Toronto.
What Is an Insurance Broker and How Do They Work in Canada?
Before diving into how to choose the right professional, it is important to understand what a broker actually does and how their role differs from other insurance representatives.
Insurance Broker vs. Insurance Agent: Key Differences
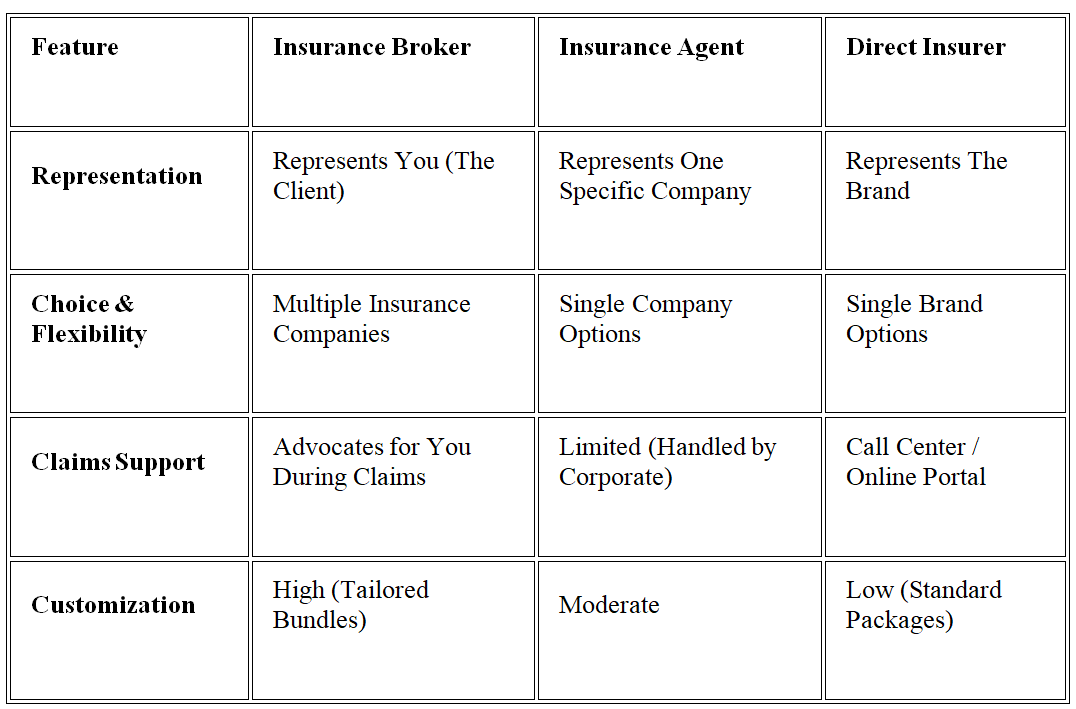
Many consumers use the terms "insurance agent" and "insurance broker" interchangeably, but in Canada, they fulfill fundamentally different roles:
- Captive Insurance Agents: An agent represents one specific insurance company. They are employed by or contracted to sell only that insurer’s products. While they know their specific policy offerings inside and out, they cannot offer you options from competing companies.
- Insurance Brokers: A broker is an independent professional who works on behalf of the client, not the insurance companies. A broker maintains partnerships with dozens of insurance providers across Canada. They compare policies, negotiate terms, and build customized coverage packages that fit your exact needs.
How Insurance Brokers Work Canada: Fees & Payment Structure
A common question for Canadians seeking financial services is: "How much does hiring an insurance broker cost?"
Understanding how insurance brokers work Canada financially gives consumers complete peace of mind. In almost all personal insurance lines (such as personal auto, home, tenant, or condo insurance), brokers do not charge clients a direct fee for their services.
Instead, insurance brokers are compensated through commissions paid directly by the insurance companies they partner with. When a broker places your policy with an insurer, that company pays the broker a percentage of the annual premium.
Because brokers work with multiple companies, they are incentivized to find you the best rate and coverage package rather than pushing a single expensive option. For complex commercial insurance policies or specialized risks, some brokers may charge a transparent administrative fee, but this is always disclosed up front.
Key Benefits of Working with an Insurance Broker in Canada
Partnering with an experienced insurance broker Canada offers several distinct advantages over shopping independently online:
Unbiased Expert Guidance
Insurance policies are legal contracts packed with technical jargon, deductibles, endorsements, and exclusion clauses. An experienced broker reviews the fine print for you, ensuring you don't face unexpected coverage gaps when disaster strikes.
Time and Money Savings
Shopping around for auto or home insurance independently requires filling out long questionnaires on dozens of different websites. A broker takes your information once, inputs it into professional underwriting platforms, and presents you with comparable quotes from top insurance carriers within hours.
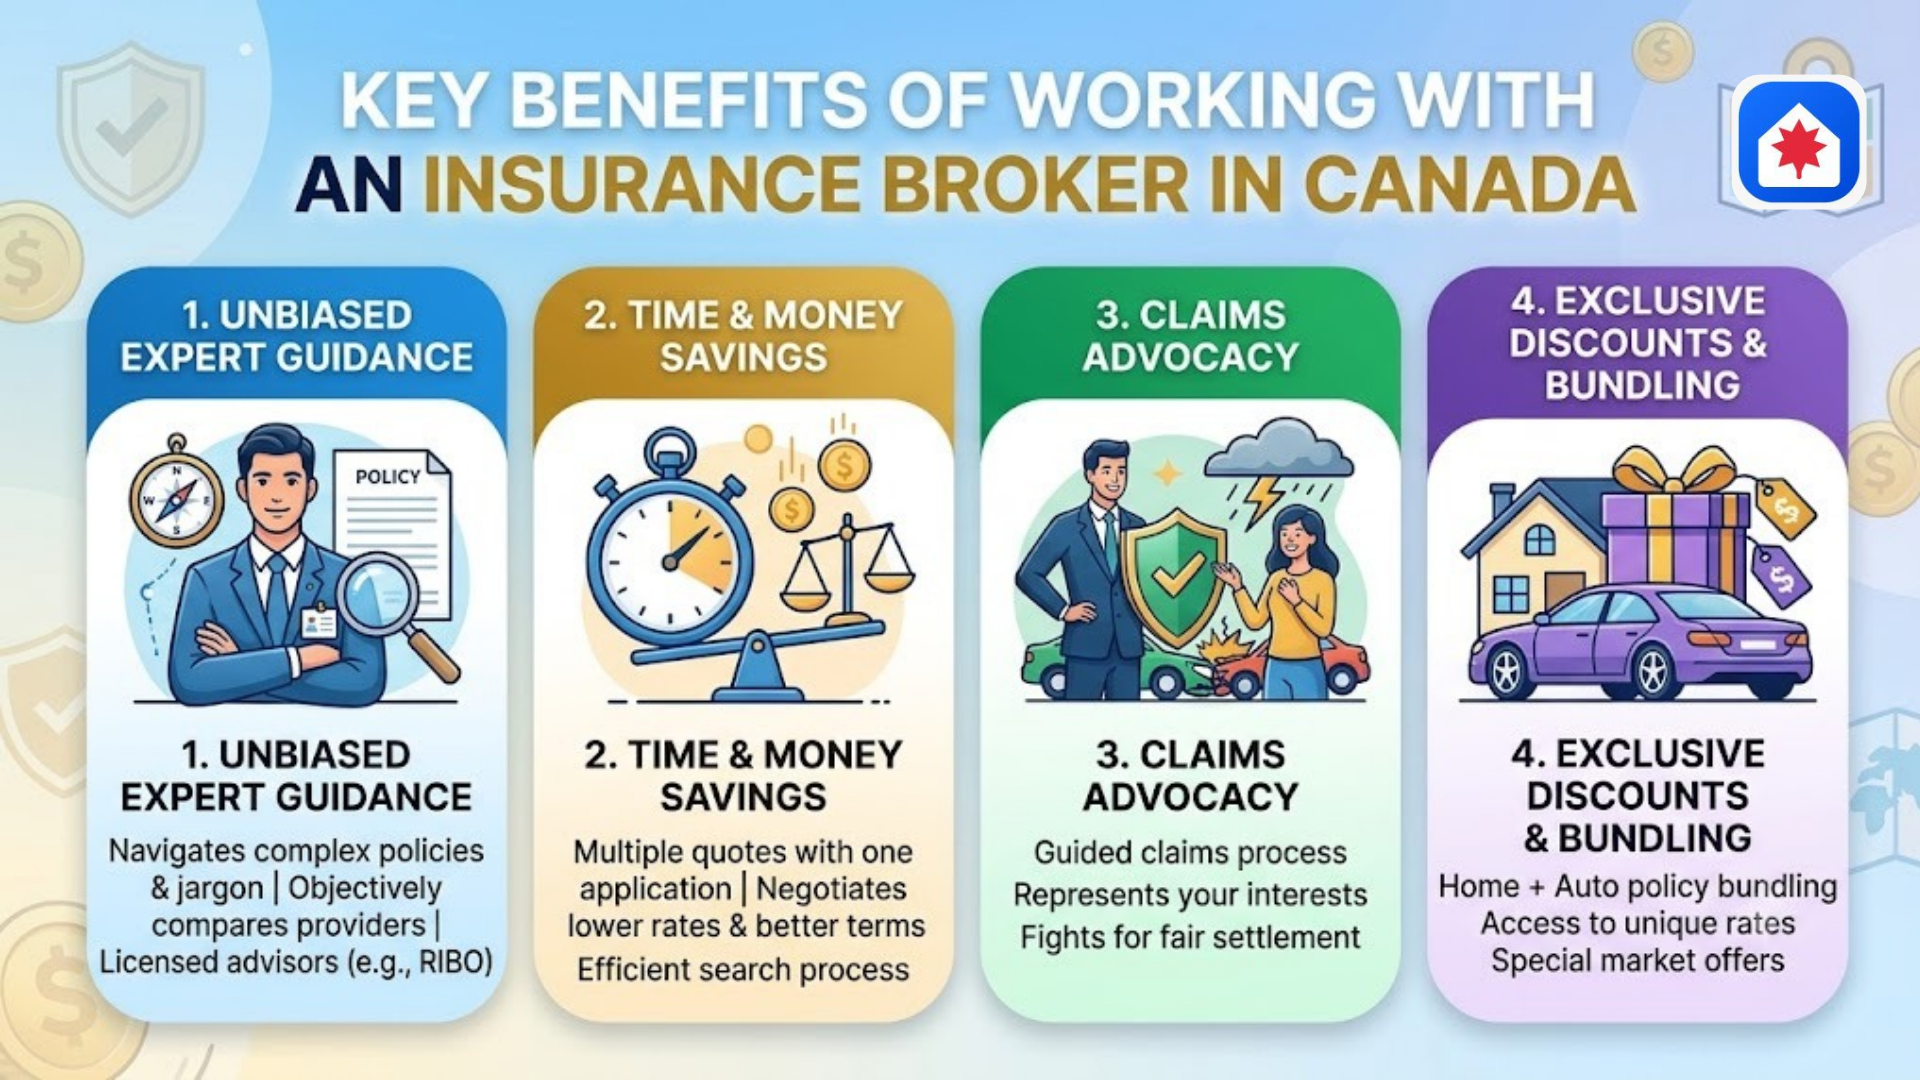
Claims Advocacy
The true value of an insurance broker shines when you need to file a claim. If you suffer a house fire, car accident, or liability lawsuit, your broker acts as your advocate. Instead of dealing with an anonymous call center, your broker guides you through the process, ensures claims are handled fairly, and pushes for prompt settlement payouts.
Exclusive Discounts and Policy Bundling
Brokers have access to specialized rates, group discounts, and policy bundling options (combining your home and auto policies) that are often unavailable directly to the general public.
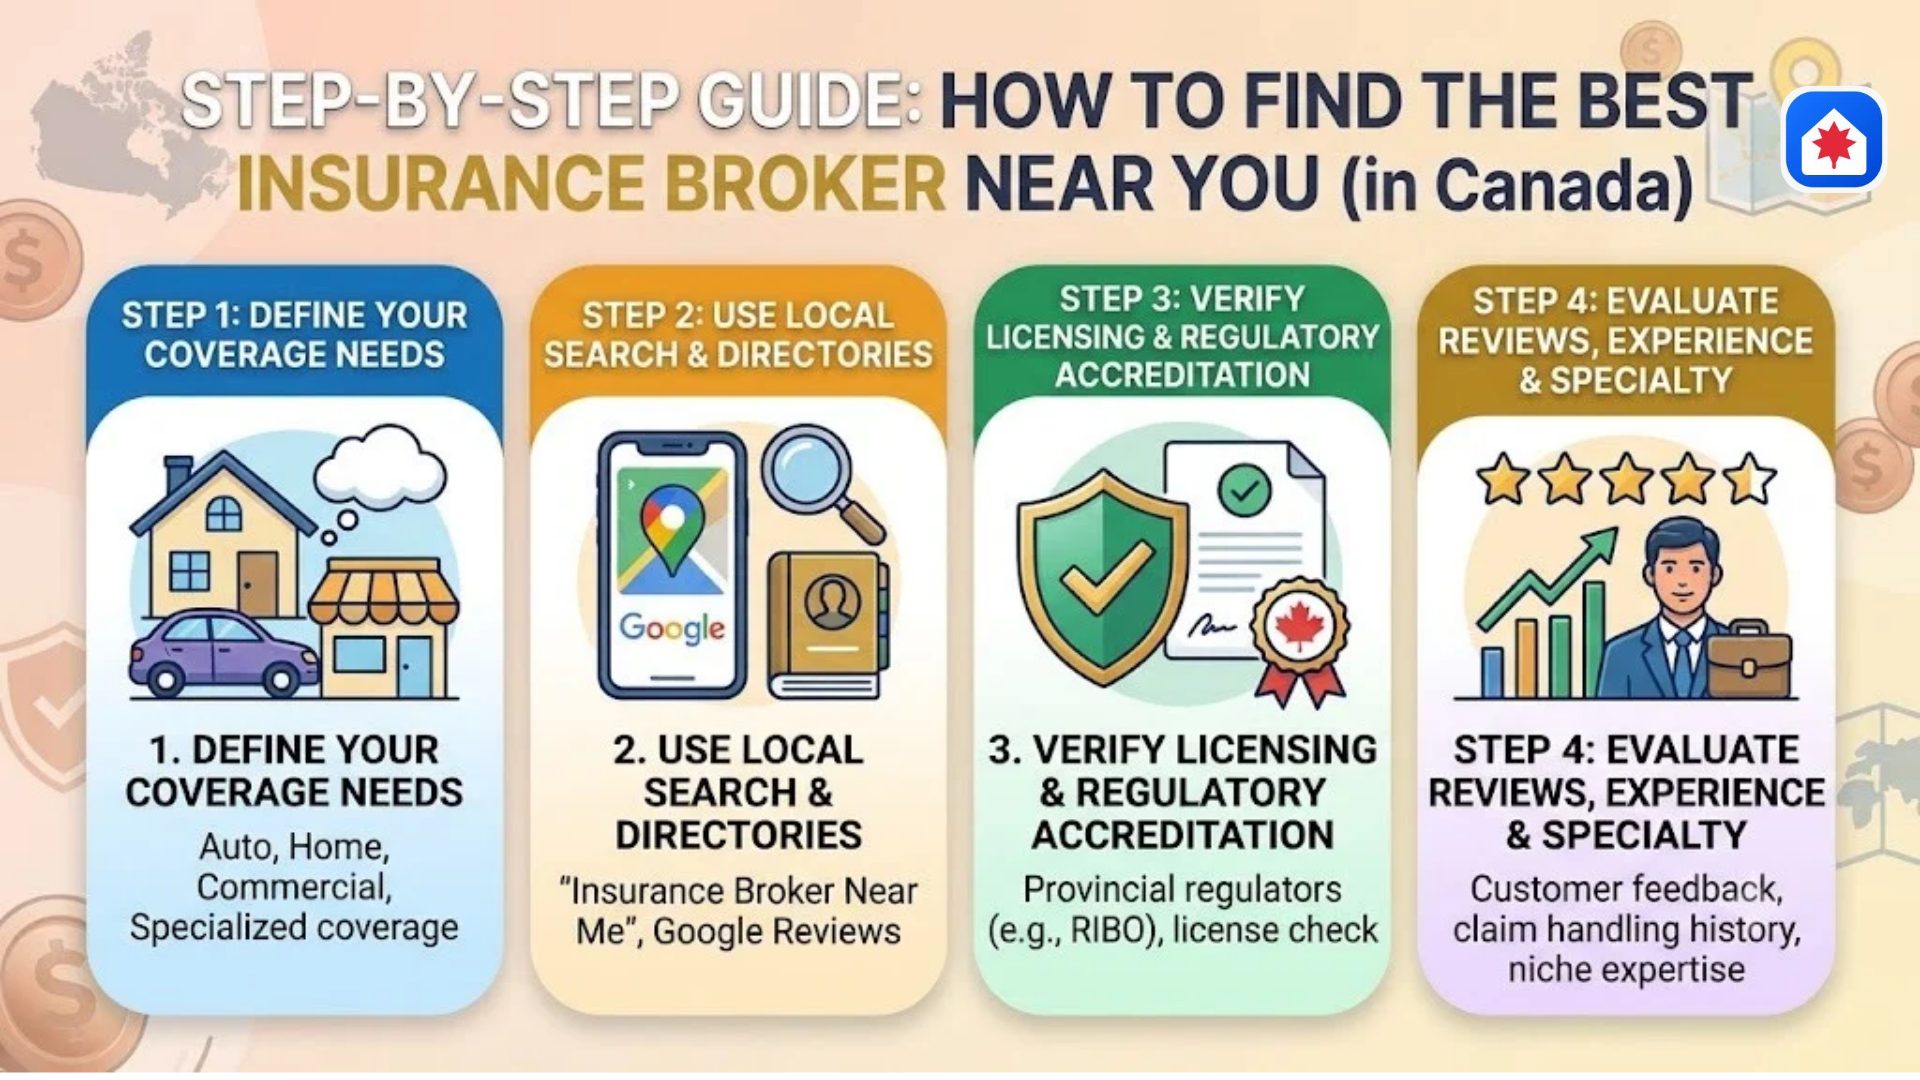
Step-by-Step Guide: How to Find the Best Insurance Broker Near You
Finding a reliable local professional requires a systematic approach. Follow these actionable steps when searching for an insurance broker near me.
Step 1: Define Your Coverage Needs
Start by identifying what type of protection you require. Are you a high-risk driver looking for affordable auto coverage? A small business owner needing general liability and professional indemnity insurance? Or a first-time homebuyer looking for comprehensive property protection? Knowing your core requirements will help you choose a broker with the relevant expertise.
Step 2: Use Local Search Strategies
When searching for an insurance broker near me, Google Maps and local business directories are excellent starting points. Look for brokerages with established physical offices in your community, consistent business hours, and strong customer ratings. A local broker understands regional risks, such as local weather patterns, crime rates, and municipal regulations.
Step 3: Check Licensing and Regulatory Accreditation
In Canada, insurance brokers must be licensed by regulatory bodies within their respective provinces. Before signing any contract, verify that your broker is in good standing:
- Ontario: Must be registered with the Registered Insurance Brokers of Ontario (RIBO).
- Alberta: Regulated by the Alberta Insurance Council (AIC).
- British Columbia: Licensed through the Insurance Council of British Columbia (ICBC/Council).
- Other Provinces: Check with your provincial Superintendent of Insurance or Insurance Council.
Regulated brokers are required to carry Errors and Omissions (E&O) insurance and adhere to strict codes of ethics and professional conduct.
Step 4: Evaluate Client Reviews and Industry Experience
Look beyond five-star ratings on search engines. Read reviews specifically mentioning how the broker handled actual claims, annual policy renewals, and customer service inquiries. A broker who communicates proactively during renewal time to re-shop your rates is invaluable over the long run.
Regional Focus: Finding an Insurance Broker in Ontario & Toronto
Insurance regulations, premium calculations, and coverage requirements vary significantly across Canadian provinces. Ontario, in particular, represents one of the most competitive and complex insurance markets in the country.
Understanding the Ontario Insurance Market
If you are looking for an insurance broker Ontario, you need a professional who understands the province’s mandatory statutory accident benefits, mandatory auto coverage limits, and private property market dynamics.
Ontario operates under a "no-fault" auto insurance system, which means your own insurer pays for your injury claims regardless of who caused the accident. Navigating these policy choices—such as opting for increased tort liability or adjusting comprehensive deductibles—requires tailored advice from a licensed insurance broker Ontario.
Navigating Premium Rates in Toronto (GTA)
Drivers and homeowners residing in the Greater Toronto Area face some of the highest insurance rates in North America due to high traffic density, frequent collisions, and elevated vehicle theft rates.
Finding an experienced insurance broker Toronto can significantly offset these steep costs. A knowledgeable Toronto broker can help local residents unlock hidden cost-saving opportunities, such as:
- Telematics & Usage-Based Insurance (UBI): Savings based on safe driving habits tracked via mobile apps.
- Winter Tire Discounts: Mandatory savings mandated for drivers using approved winter tires.
- Security & Anti-Theft Discounts: Rate reductions for installing approved vehicle tracking devices or home security systems.
- Multi-Vehicle and Multi-Policy Discounts: Combining auto, home, condo, or tenant insurance under one carrier.
Whether you reside in downtown Toronto, Scarborough, North York, or Missisauga, an insurance broker Toronto understands localized postal code pricing variations and can identify carriers offering the lowest rates for your neighborhood.
Essential Questions to Ask Before Hiring an Insurance Broker
When interviewing a potential broker, ask these targeted questions to evaluate their capability and transparency:
- "Which insurance companies do you represent?"
- Why ask: Ensure they partner with a broad range of reputable insurance carriers (e.g., Aviva, Intact, Travelers, Wawanesa), giving you true market choice.
- "Are there any additional service or brokerage fees on top of my policy premium?"
- Why ask: Confirm complete financial transparency upfront.
- "How does your team assist clients during the claims process?"
- Why ask: A great broker provides dedicated claims support rather than handing you off directly to an insurance carrier's generic hotline.
- "Are all of your advisors fully licensed by provincial regulators like RIBO?"
- Why ask: Confirms legal standing and professional accountability.
- "Do you review my policy automatically at renewal time?"
- Why ask: The best brokers re-shop your policy annually to ensure your rates remain competitive as market conditions change.
Red Flags to Avoid When Selecting a Broker
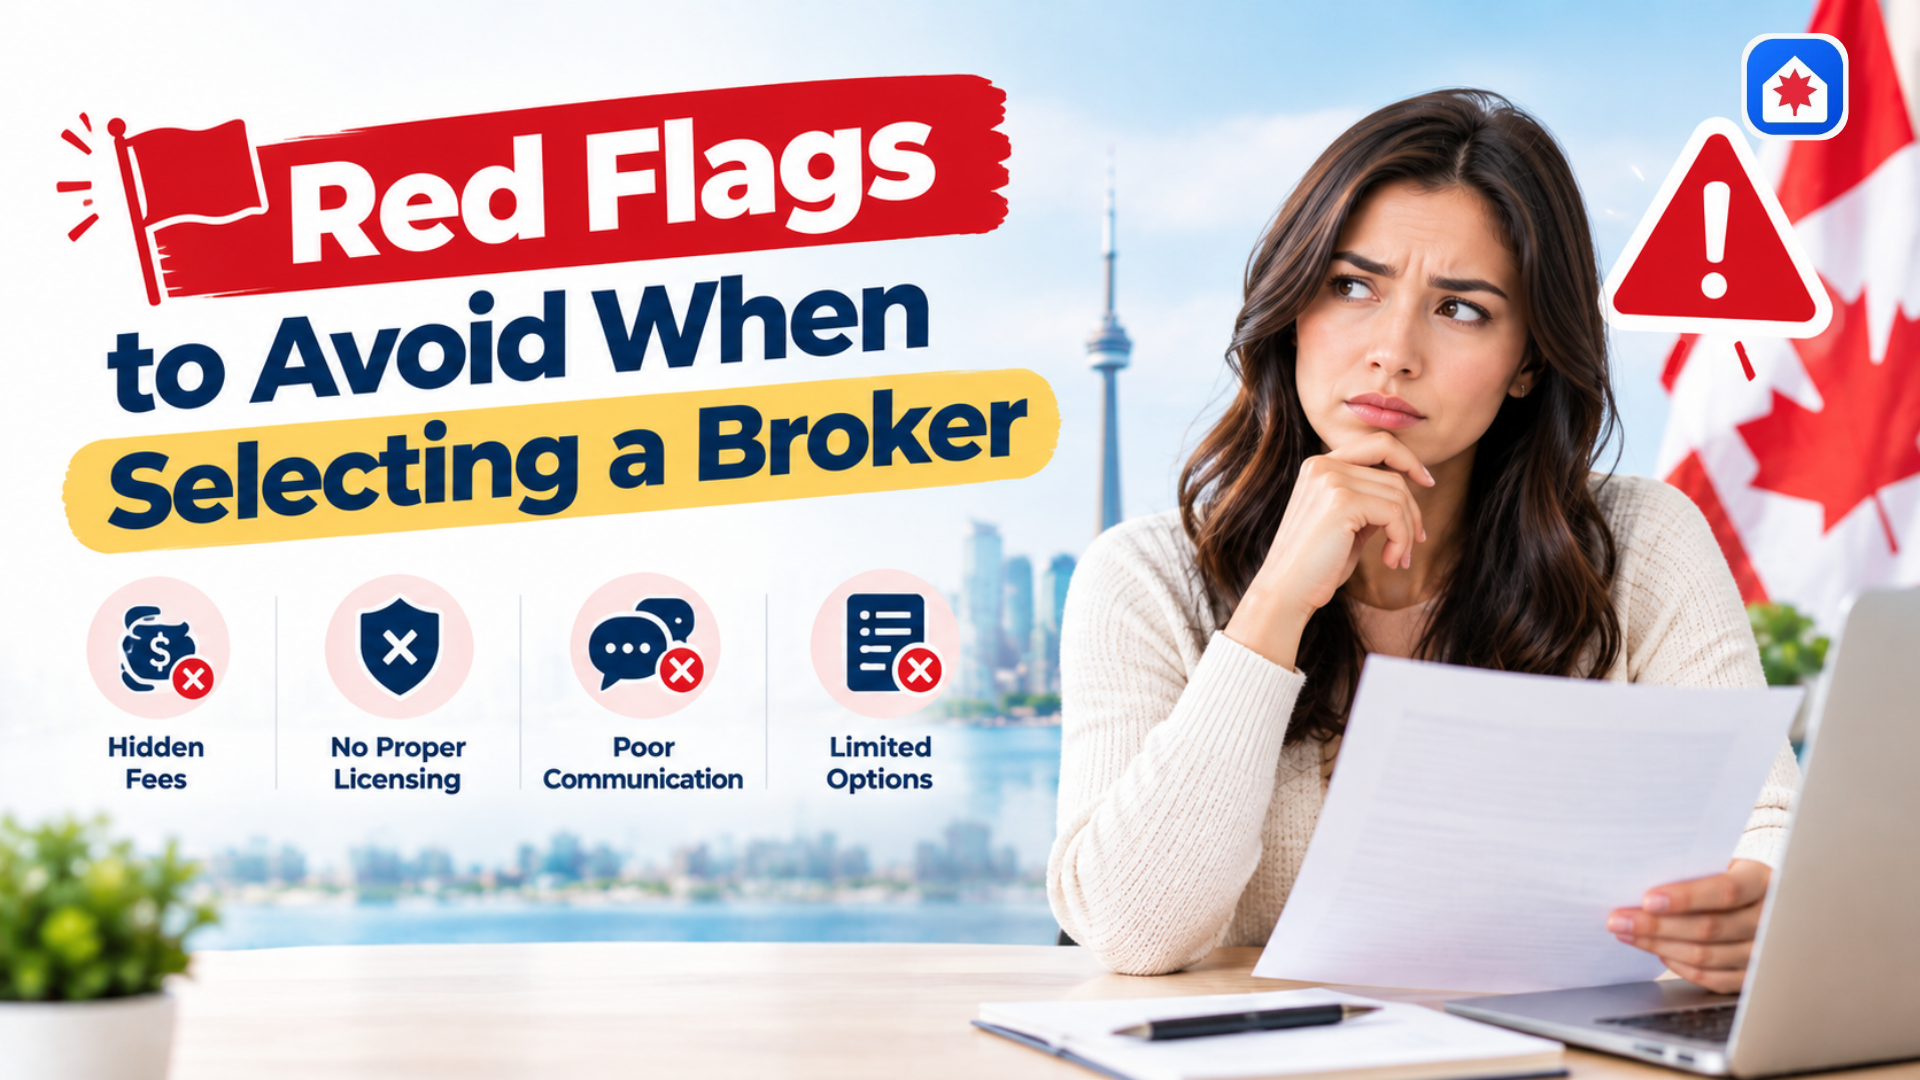
Protect your finances by watching out for these red flags during your search:
- Unrealistically Low Quotes: If a quote seems significantly lower than all competitors, ensure the broker has not quietly stripped away critical coverage limits or increased deductibles to unmanageable levels.
- Pressure Tactics: Avoid brokers who push you to sign immediately without allowing you time to review policy documents and disclosures.
- Lack of Licensing Transparency: If a broker cannot quickly provide their license number or provincial regulatory registration, look elsewhere immediately.
- Poor Communication: Difficulty reaching a broker during initial sales inquiries usually indicates poor customer service when you eventually need to file an urgent claim.
Conclusion: Take Control of Your Insurance Coverage Today
Finding the right coverage does not have to be a stressful or overly expensive process. By partnering with a qualified insurance broker Canada, you gain an independent advisor who advocates for your financial interests, simplifies policy jargon, and ensures you never pay more than necessary.
Whether you need specialized rates from an insurance broker Ontario, hyper-local guidance from an insurance broker Toronto, or are searching for a trusted insurance broker near me, taking the time to verify credentials, read reviews, and ask the right questions will pay dividends for years to come.
Start protecting your home, vehicle, or business with confidence. Reach out to a licensed Canadian insurance broker today to review your current policy and request a competitive quote comparison.
Thank you for reading our article!